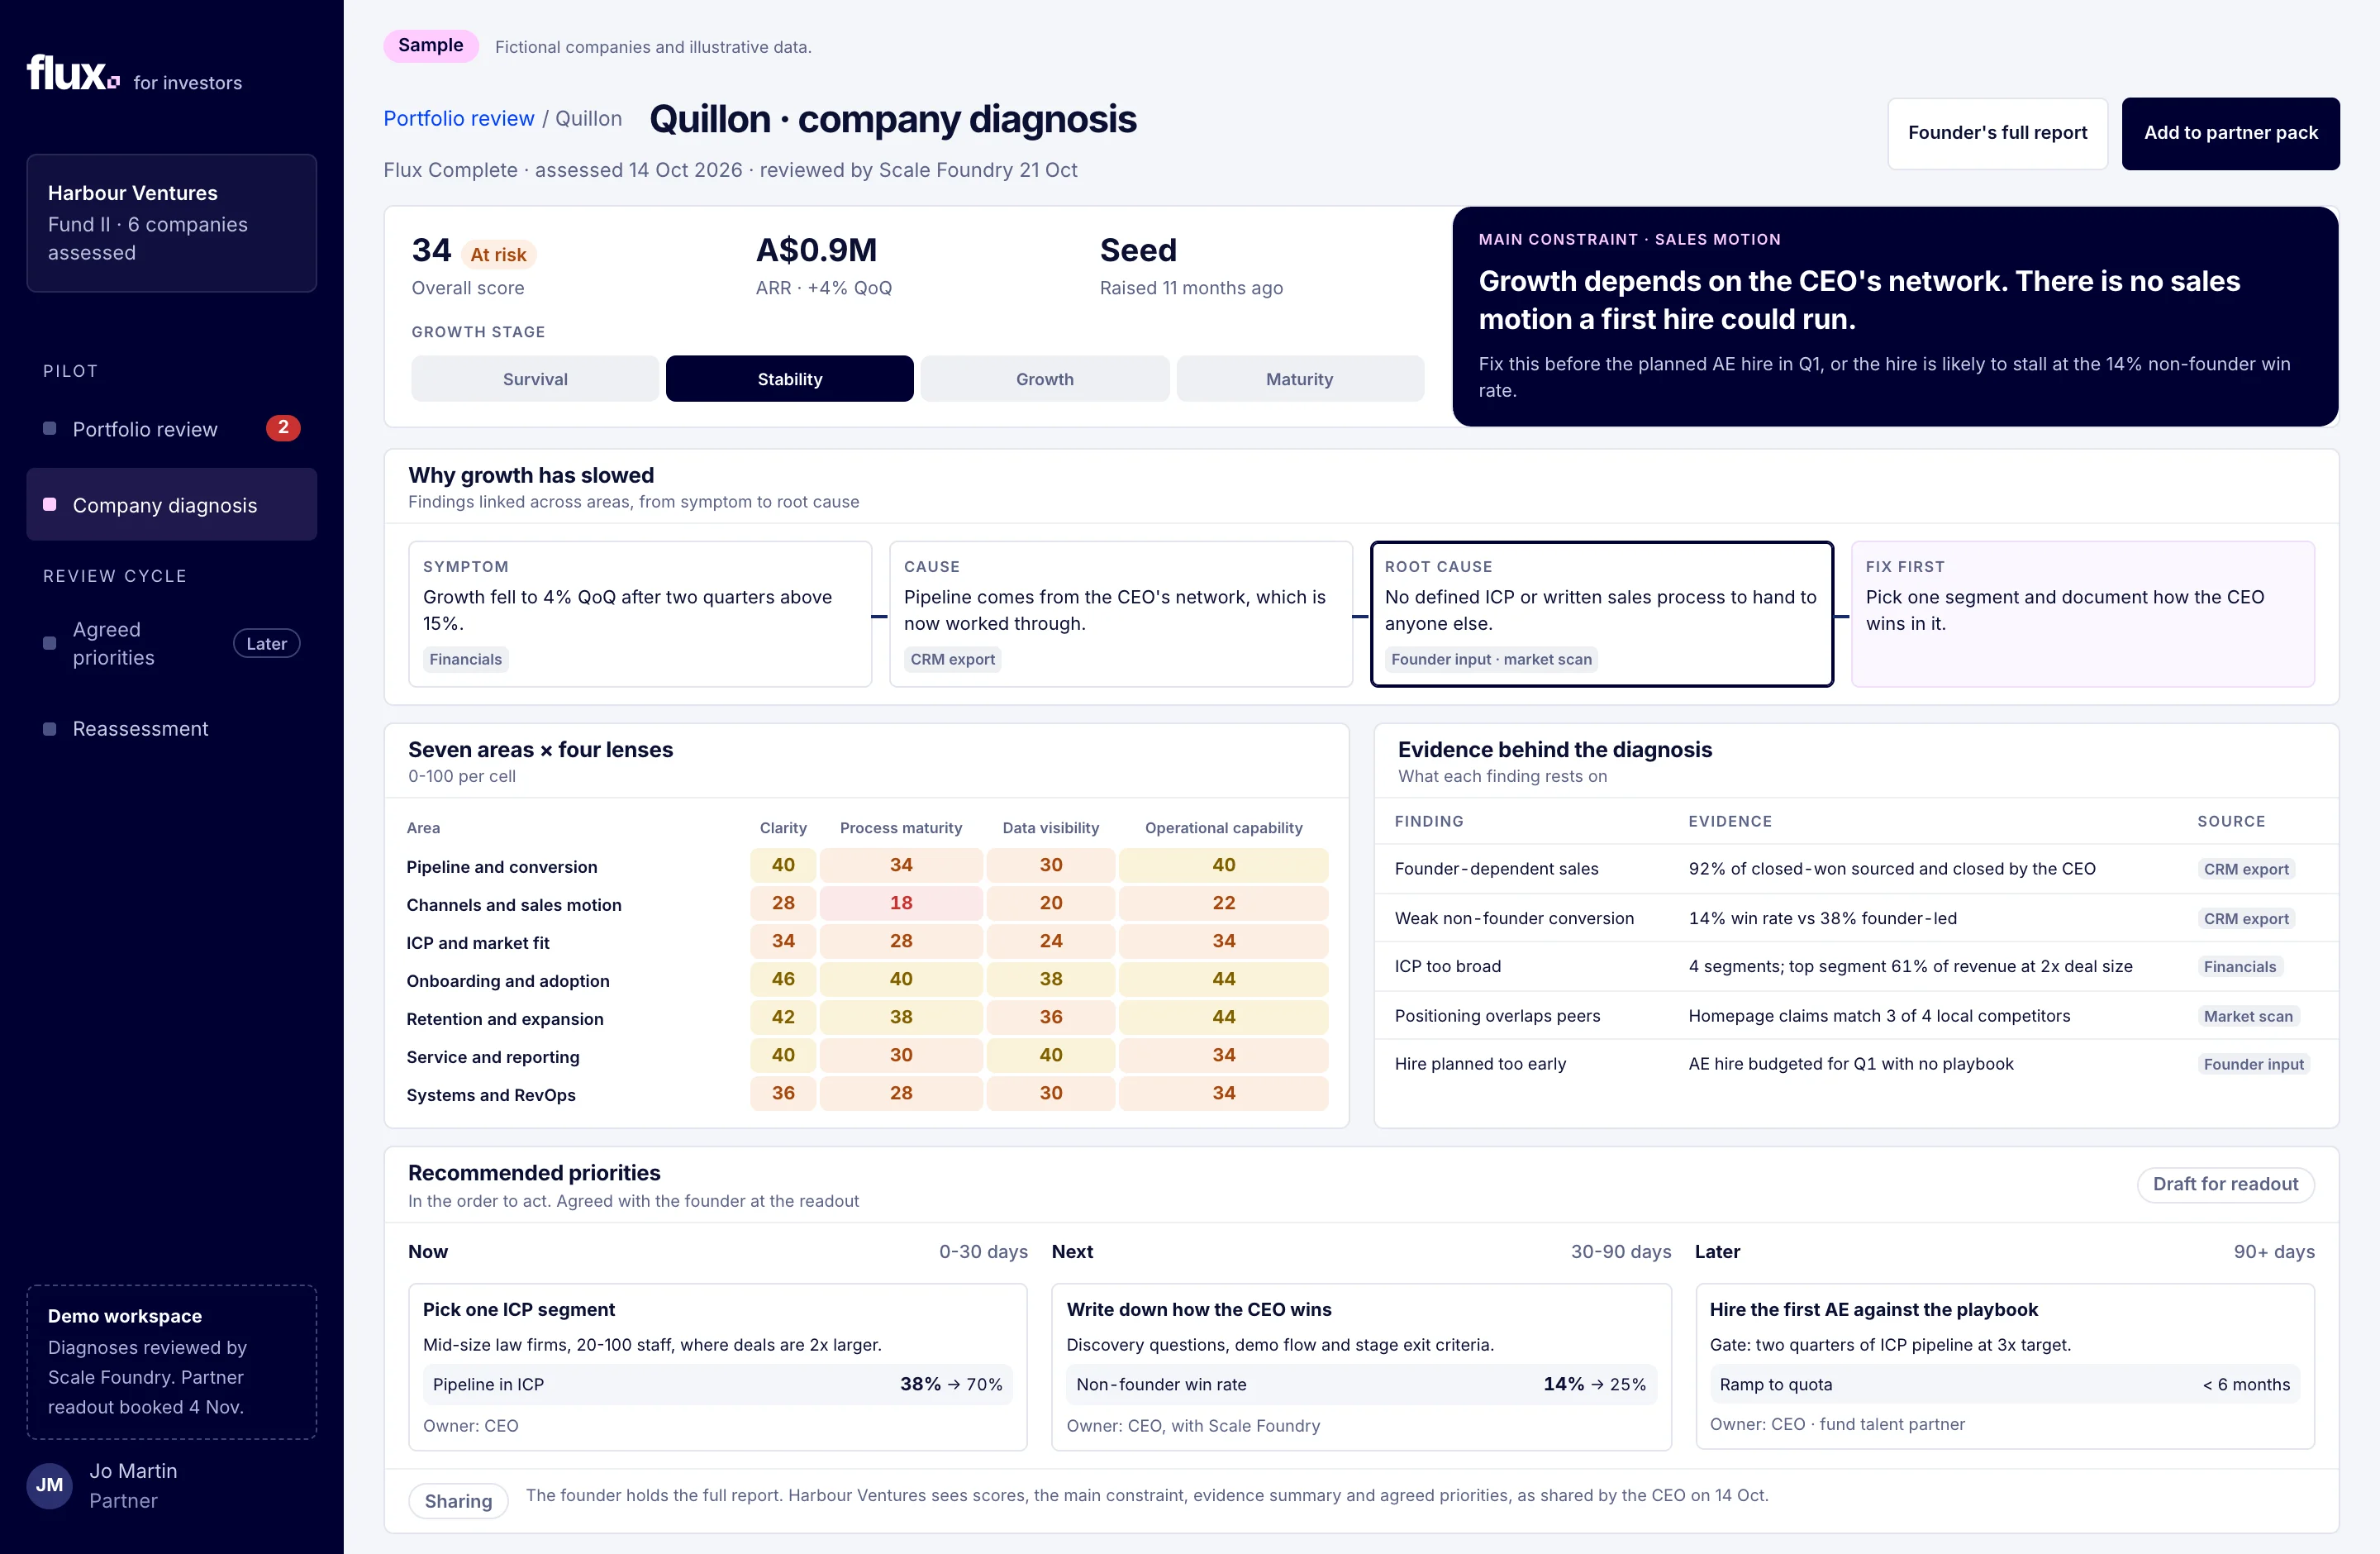
Quillon
The CEO still sources and closes almost every deal.
- CRM export92% of closed-won sourced and closed by the CEO
- CRM export14% win rate on non-founder deals vs 38% founder-led
CRM data, financials, market position and the founder's view, read together and reviewed by an operator. Ranked by where to step in, with the evidence behind each call.
Pilot: up to 5 companies · A$4,950 + GST · 3-4 weeks · 2-3 hours per founder

Rank the companies. See where to step in first.
Your monitoring tool shows the numbers. The review explains them: where to step in first, the evidence behind each call and patterns across the fund.
The CEO still sources and closes almost every deal.
Net revenue retention is 96%. Nobody owns expansion.
Renewals surface 21 days out, too late to save accounts.
Sample review · fictional companies, illustrative scores.
Two of these three companies are held back by retention and expansion. One portfolio session can address both, instead of two separate fixes.
Open a company to connect the slowdown to its root cause, inspect the sources and agree what to fix first.

See how the findings connect across the revenue engine.
CRM data, financials, founder input and market research behind each finding.
A consistent view of the strengths and gaps holding growth back.
Priorities with an owner, a measure and an order to act.
Assess each company's revenue engine and operating metrics. Identify the constraints and record the starting point.
Review the findings with partners and founders. Choose the actions, owners and measures.
Compare fresh evidence with the baseline. On the annual plan, re-measure every 6 or 12 months - your choice - to explain movement and update the priorities.
A growth plan they'll want, not another reporting request. Free to the founder - your fund covers it. They get their full Flux Complete report, a prioritised plan and a 30-minute readout.
2-3 hours over two weeks for the initial assessment, a CRM export and recent financials. Focused updates at each reassessment.
Scores, the main constraint, an evidence summary and agreed priorities. The founder approves what is shared and holds the full report. Over time, you build a documented baseline and progress record for each company - evidence of your support, ready for LP reporting.
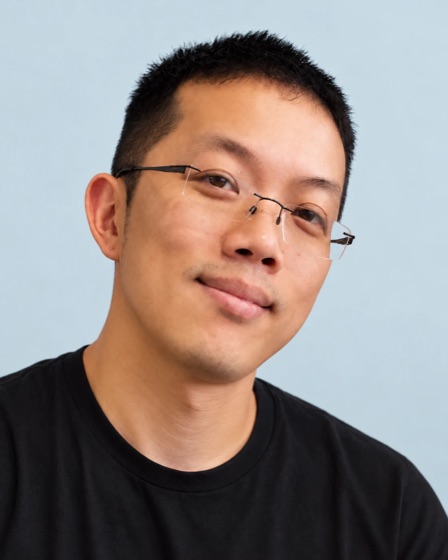
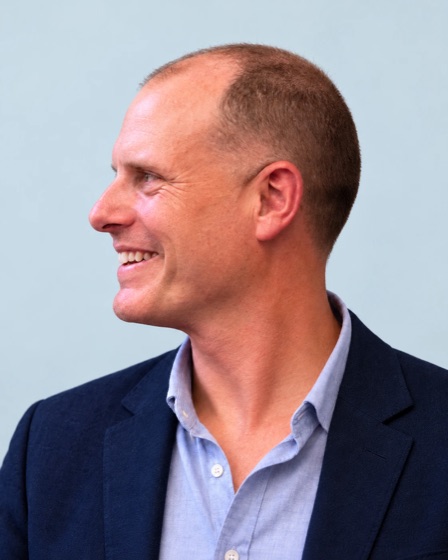
Scale Foundry's operators build and review every diagnosis, bringing experience in B2B go-to-market and revenue operations.

Adrian Lowe
Co-founder, Commercial and GTM
20+ years building go-to-market from the ground up in early-stage tech across Silicon Valley and Australia, including PaperCut and carsales.com.au.

Marty Schneider
Co-founder, Customer Operations
Two decades setting up and scaling customer success, revenue operations and service delivery, including at MYOB and Intuit.
One portfolio price, paid by the fund. Free to every founder.
For our first three funds. Fund-paid, free to founders.
A$4,950 + GST
For up to 5 companies, paid by the fund.
100% credited to an annual plan signed within 60 days.
Annual plans from A$12,000 + GST a year for up to 10 companies. Re-measure each company every 6 or 12 months - your choice - with a portfolio review after each round. Free to every founder.
Keep it. Tools like Carta, Standard Metrics and Visible collect the numbers and handle LP reporting. Flux works on what sits underneath: why a company's revenue is moving, the evidence behind it, and what to fix first, reviewed by an operator. Your tool shows a number moved. Flux explains why.
It's being shaped with our founding pilot funds. In the pilot, you get the portfolio review and company diagnoses as reports and readouts. Pilot funds see the dashboard first and help decide what it shows.
We compare scores and operating metrics with the baseline and previous assessment, investigate the likely drivers, and update the priorities. On the annual plan, you choose to re-measure every 6 or 12 months, with a portfolio review after each round.
The founding pilot is A$4,950 + GST for up to 5 companies, paid by the fund, for our first three funds. It is 100% credited to an annual plan signed within 60 days.
No. The fund covers it. Founders get their full report and a readout, and choose what the fund sees.
As support, not monitoring. The fund covers it, founders get an operator-reviewed diagnosis and plan they'd normally pay for, and they choose what the fund sees.
Founder input, a CRM export and recent financials. They receive the full report and approve the scores, evidence summary and priorities shared with the fund. Data is never shared with other funds or companies.
Company data is held in Scale Foundry's business account on Google's secure cloud infrastructure, and only the Scale Foundry team working on the diagnosis can access it. AI tools support the research and synthesis under business terms that don't use your data to train models, and nothing is ever shared with other funds or companies. Data is deleted 12 months after the pilot ends unless you continue on an annual plan, or sooner on request, and we're happy to sign a mutual NDA before anything is shared.
B2B SaaS, seed to Series B, with at least A$500K ARR. We'll discuss fit during the demo.
We'll walk you through a sample portfolio review and company diagnosis, and discuss a pilot across up to five of your companies.